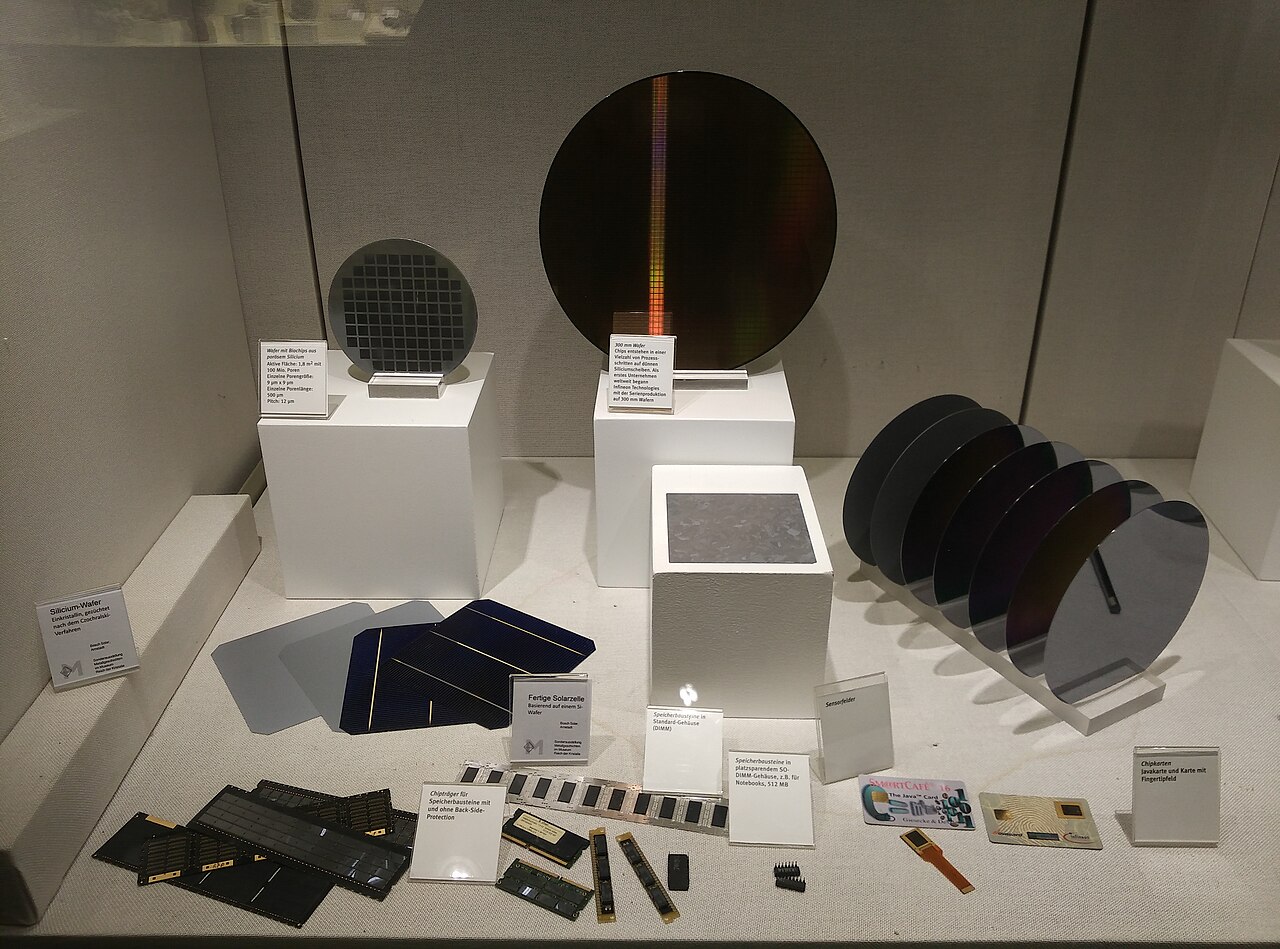
A single wafer barely wider than a dinner plate can hold billions of transistors.
Billions of those wafers shipped this year, from fabs in Taiwan, South Korea, and Arizona.
One quarter alone generated more chip revenue than the entire global market produced in any full year before 2021.
The revenue figures that came back were unlike anything the industry had ever printed.
So what broke open the floodgates, and will any of it hold?
How a chip goes from sand to a number that large
Every semiconductor begins as a silicon ingot sliced into paper-thin discs, then subjected to dozens of photolithography steps that etch circuits measured in nanometers, widths roughly a thousand times finer than a human hair. Advanced logic nodes like the 3-nanometer processes now running at volume use extreme ultraviolet light to print those features, and each standard EUV exposure machine costs roughly $183, 220 million; the newer High-NA generation used for sub-3nm nodes costs around $380 million and occupies a room the size of a house.
But the price of a chip is not set by the cost of raw silicon. It is set by the complexity of what is printed on it. AI accelerator chips, the processors that run large language models and train neural networks, pack tens of billions of transistors and sell for tens of thousands of dollars per unit.
When those become the dominant product category, the revenue math changes fast. High-bandwidth memory stacks multiple layers of DRAM into a single package, has become the essential companion to every AI accelerator, and its added complexity lifted average selling prices sharply into territory old forecasts never assumed.
The quarter that rewrote the record books
The Semiconductor Industry Association reported on August 6 that global semiconductor sales reached $403.3 billion during the second quarter of 2026, an increase of 35.1% compared to Q1 of 2026. That single-quarter figure is larger than the entire market produced in the full calendar year of 2013.
May alone hit $120.6 billion, the highest monthly total ever recorded at that point, and the industry achieved it while growing month-over-month for fifteen consecutive months. June then printed another record of $134.5 billion, a 123.6% increase compared to June 2025.
Americas-based demand led the charge. Year-over-year sales in April were up 115.8% in the Americas, 78.6% in China, and 54.7% in Europe. That breadth matters: when every major region moves together, the upswing is structural, not regional.
Where the numbers come from and what forecasters missed
Global chip sales reached $791.7 billion in 2025, up 25.6% on the prior year. That was already a full-year record, yet within months it became a baseline the current pace had left far behind. Early in this year, the industry’s main trade body projected annual sales would reach roughly $1 trillion in 2026. The industry blew past that figure before summer ended.
The trade body then endorsed a spring forecast projecting annual global sales will grow by 90 percent to $1.5 trillion. As recently as 2024, mainstream industry forecasts placed $1 trillion in annual chip sales around 2030. The gap between that projection and reality is now measured in years, not months.
According to an analysis by Semiconductor Intelligence, the 25% quarter-over-quarter growth from Q4 2025 to Q1 2026 was the highest in the more than 40-year history of WSTS statistics, surpassing the previous record set during the sharp recovery following the 2008, 2009 financial crisis. That trajectory is feeding a broader buildout, where the compute demands of frontier models are translating directly into chip orders.
Where the surge does not reach and what could interrupt it
Not every segment is riding the same wave. Consumer electronics chips, the microcontrollers inside appliances and display drivers inside budget phones, are growing far more slowly than AI silicon. The headline revenue number is pulled upward by a narrow category of high-value parts, so the broader economy of semiconductor buyers is not uniformly sharing in the boom.
Supply chain concentration remains a real constraint, and the capital flowing into AI cloud platforms depends on it holding. Taiwan manufactures over 90 percent of the world’s most advanced logic chips, and South Korea leads in high-bandwidth memory. A typhoon, an export-control escalation, or a power shortage could interrupt shipments in ways the revenue figures do not yet reflect.
Memory prices surged partly because suppliers chose to prioritize high-margin parts over standard flash, a deliberate allocation choice that can reverse if new capacity arrives faster than expected. The chip industry has been through that inventory cycle before.
What a $1.5 trillion chip market means for everyday technology
The revenue record is an industry number, but its effects reach well past the factory floor. The platforms driving the boom are what run the AI tools now embedded in search, productivity software, and consumer devices across the US.
For American consumers, the most immediate signal is that chip pricing for high-end AI hardware is not coming down quickly. Data center operators are paying record prices per chip and passing the infrastructure cost upward into cloud service pricing. That dynamic is part of why enterprise software bills have climbed even as the underlying models have improved.
Even so, the scale of investment flowing into semiconductor manufacturing is historically without precedent, and scale eventually produces efficiency. In 2027, global chip sales are projected to exceed $1.9 trillion, a figure that would have been dismissed as fantasy five years ago. The fabs being commissioned today will determine whether that trajectory holds through the rest of the decade.
