Every week, a quiet ritual plays out in apartments and shared houses across America.
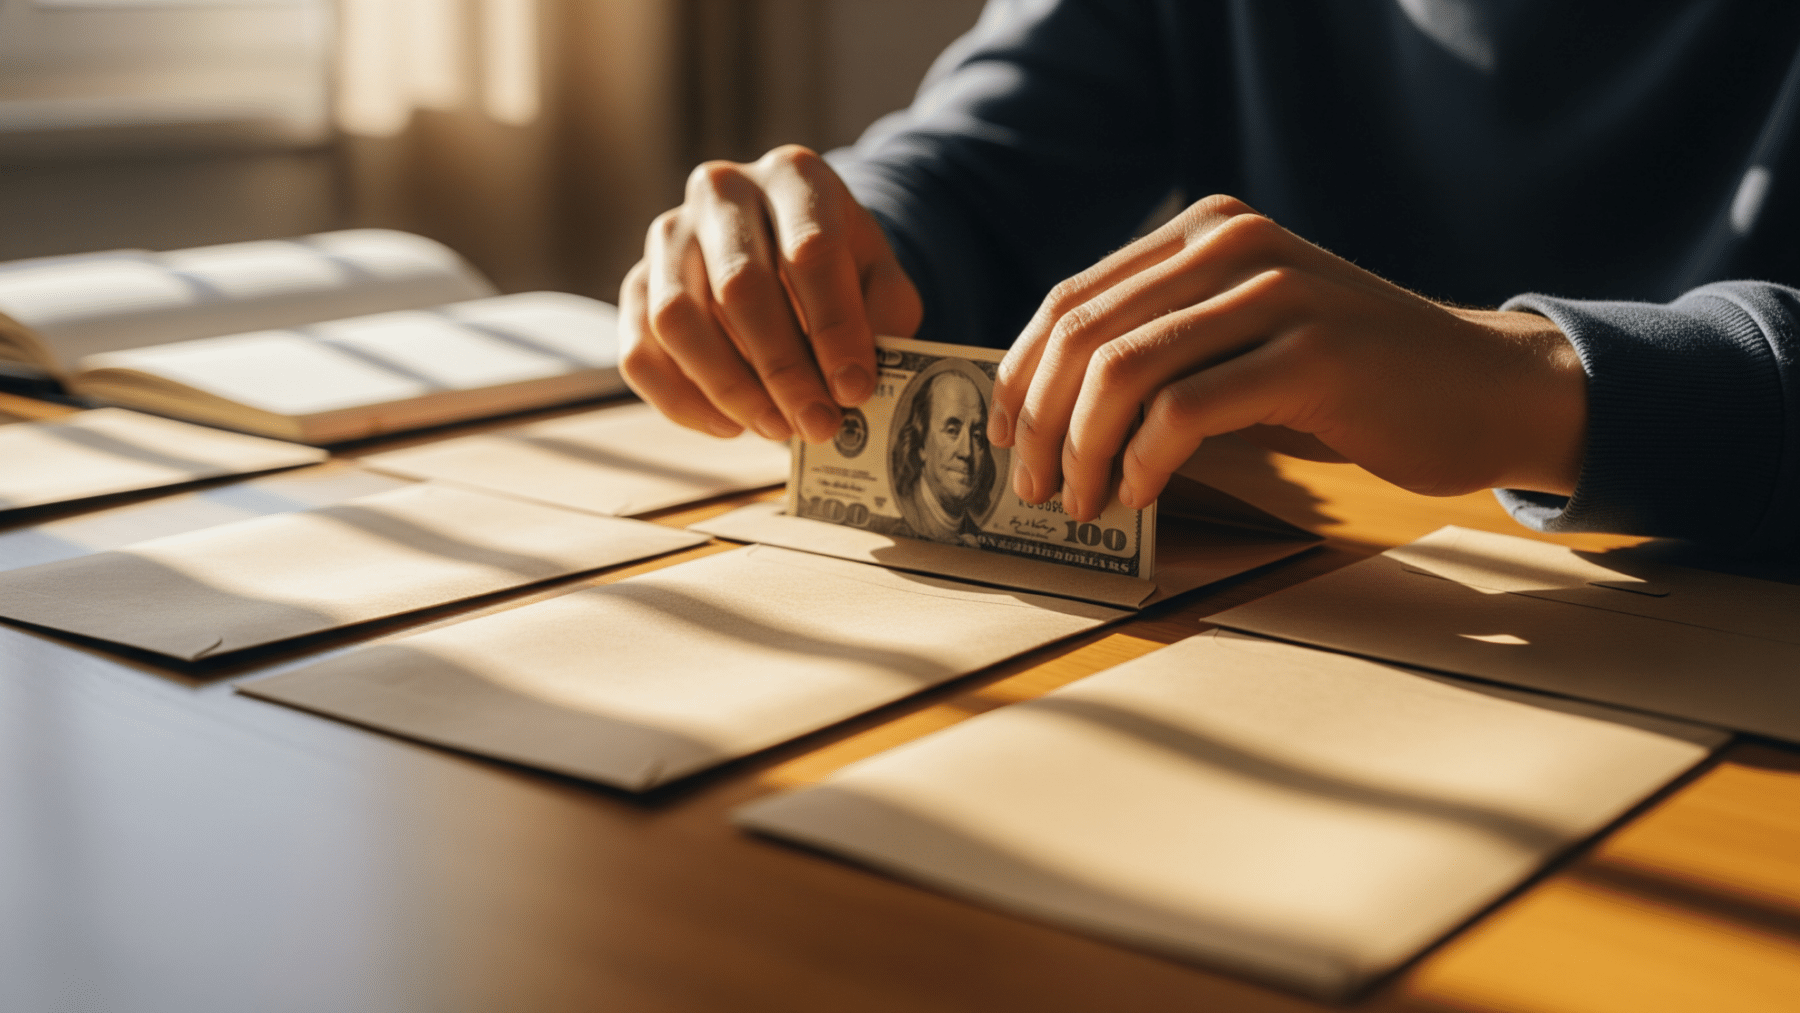
Someone pulls a stack of bills from an ATM, opens a budgeting binder, and starts sorting cash by hand into labeled envelopes, groceries, rent, savings, fun money.
It looks like something lifted from a grandparent’s kitchen drawer in 1974.
But the people doing it are overwhelmingly in their early twenties, and the numbers behind the habit just got a lot more interesting.
A budgeting trick older than credit cards is suddenly everywhere again
The method is called cash stuffing, and it is almost comically low-tech.
The practice involves dividing currency into envelopes labeled for groceries, rent, utilities, savings and other expenses.
The appeal is simple: once an envelope is empty, the budget for that category is gone.
No app. No algorithm. No notifications.
It may feel like a digital-age discovery. It is actually one of the oldest forms of household budgeting. Financial experts were teaching it to Baby Boomers’ parents decades before Venmo existed.
So why is it trending in 2026?
The generation that grew up swiping cards is now deliberately choosing paper
Gen Z, the first truly digital cohort, raised on contactless payments and one-click checkout, is the engine behind the revival.
That tension is real. Tapping a phone feels almost weightless; handing over physical bills does not. Of Gen Z who use cash to pay for purchases, 59% say they do so as a way to budget their money, and 64% say they spend less money when they pay with cash.
Cash stuffing has gone viral on TikTok and Instagram, where users film themselves sorting every dollar by category and sharing their progress with online audiences.
The same generation that splits everyday purchases into four installments is also pulling money out of the bank and sorting it by hand, two opposite responses to the same underlying anxiety about overspending.
Watching cash physically accumulate in a “vacation” or “emergency fund” envelope gives many people a greater sense of satisfaction than seeing a number on a screen.
The income picture makes this even harder to explain on the surface
It would be easy to assume that young adults are turning to cash because they have so little of it.
And budgets are genuinely tight. Gen Zers across the world say they feel stressed about their finances, with a sustained period of high inflation, increased living costs, and high levels of student debt contributing to that stress.
A rising proportion of Gen Z is saving money, with Bank of America’s Better Money Habits report finding 66% are currently saving, up from 63% the prior year. Yet housing costs remain a notable challenge, with 29% of Gen Z respondents saying they are a top barrier to their financial success.
But here is what the anxiety narrative misses: this generation is actually saving at a rate that older cohorts rarely match.
McKinsey’s State of the Consumer 2025 report found that the average 25-year-old Gen Zer has a household income of $40,000, which is 50% higher than the average baby boomer’s income was at the same age, accounting for government transfers, inflation, and taxes.
The 36.2% savings rate that reframes everything about this story
Here is the number that lands differently once you know the context.
Despite having lower incomes than older consumers, Gen Z saves 36.2% of take-home pay, compared with 26.5% for everyone else.
That gap is not small. It is nearly ten percentage points above the national average, and it is being driven at least in part by the envelope-and-binder habit that looks so old-fashioned on the surface.
The data also found that 85% of Gen Z consumers saved for larger purchases while growing up, suggesting disciplined saving habits formed well before adulthood.
The target those savers are chasing is also striking. Gen Zers on average believe an annual salary of $587,797 and net worth of $9.47 million are needed when they envision “financial success,” according to Empower, a salary figure nearly six times higher than the equivalent cited by Baby Boomers.
That ambition, combined with the broader squeeze on American household budgets, helps explain why a generation raised on apps is hunting for any tool that makes saving feel real and controllable.
The data point to a generation that places considerable value on planning ahead, even while navigating higher housing costs, student debt and elevated everyday expenses.
What the envelope in the drawer actually says about a whole generation’s future
The cash-stuffing revival is not really about envelopes. It is about visible control in a world that makes spending invisible.
A study by NielsenIQ, GfK and World Data Lab found that Gen Z’s spending power is projected to grow to $12 trillion by 2030, a scale that will rival or surpass every generation before it.
A generation building toward a $587,800 finish line while sorting paper envelopes on a Tuesday night is playing a longer game than the stereotype suggests.
Gen Z spending is growing twice as fast as previous generations’ spending did at the same age and is on pace to eclipse baby boomers’ spending globally by 2029.
The PYMNTS Intelligence research on the trend finds banks are now studying how to build digital versions of the same envelope system directly into mobile apps, because the underlying behavior turns out to be something customers actually want, whatever the medium.
Grandma’s method, it turns out, was ahead of its time.
