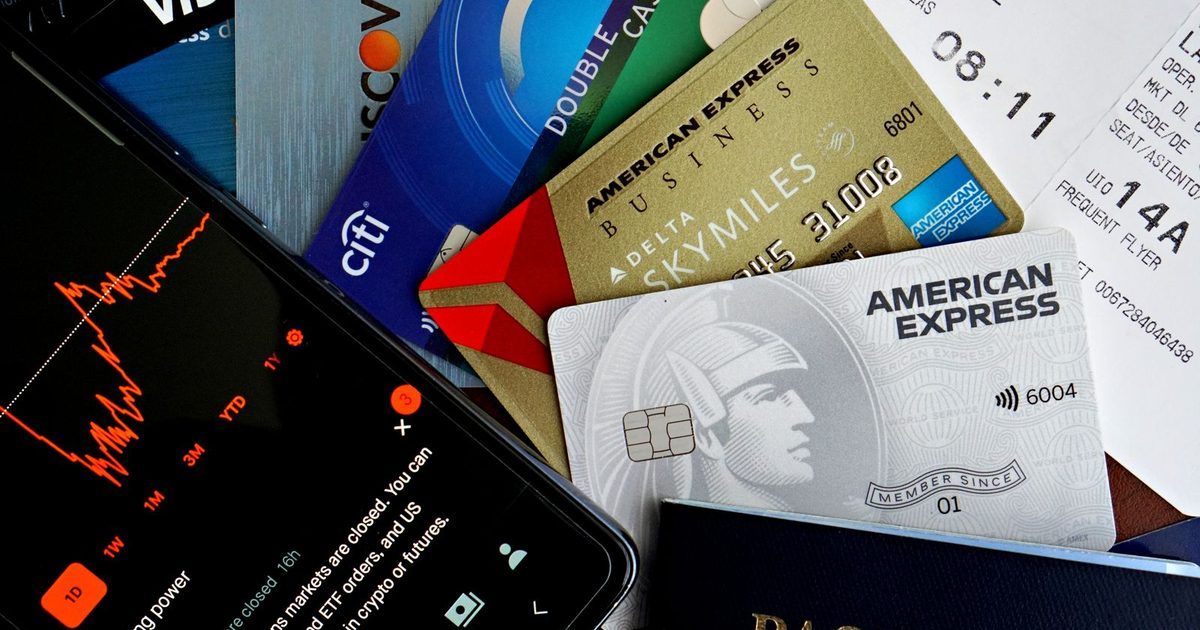
A boarding pass sits folded next to a stack of plastic on the kitchen counter.
The card promised free flights, hotel nights and airport lounges.
Months later, the points balance has not moved, and neither has the owner’s travel plans.
Somewhere between the glossy welcome offer and the actual trip, something quietly breaks down.
A fresh national survey just put a number on exactly how often that happens.
So why do so many people pay a steep annual fee for rewards they never touch?
How a points balance quietly disappears before anyone notices
Most travel cards do not revoke points with a dramatic warning. Instead they rely on inactivity clocks that start ticking the moment a cardholder stops charging purchases or redeeming miles for a set stretch, often twelve consecutive statement cycles.
Several major issuers advertise that points never expire as long as the account stays open and active, which sounds generous until a reader notices the condition buried in that sentence. Points will expire if there is no reward, purchase, or balance activity on the account for 12 consecutive statement cycles on some popular no-fee cards.
A cardholder who opens a card for a single trip, uses it twice, then switches back to a debit card can watch a year of accumulated miles vanish without a clear alert. So a points balance can look perfectly safe inside a bank’s app while the airline miles behind it quietly lapse on a separate calendar nobody checked.
Inside the wallet where the fee and the forgotten rewards sit side by side
Picture a typical cardholder’s wallet: a premium card with a fee stretching from under a hundred dollars to $795, raised in June 2025, or $895 for American Express’s flagship Platinum card, now one of the most expensive cards on the market . Between the two sits the implicit bet that travel perks and points will more than cover what the bank charges just to carry the card.
That bet only pays off with deliberate use. A $95 mid-tier card earning 2X points, worth about a cent each, needs roughly $4,750 in annual spending just to break even on the fee, before anyone touches the travel credits or lounge visits stacked on top.
Anyone who treats the card as a drawer item rather than a daily driver is already behind.
This is the same gap that shows up in similar everyday money habits, the kind GCN has tracked in how often unused capacity quietly becomes a sunk cost nobody budgeted for, whether it is a parking lot or a points account sitting dormant.
What the new survey found when it asked a thousand Americans directly
BestMoney surveyed 1,000 Americans on travel credit cards this year about how they pay for travel, and the headline number is stark. The survey found that 35.7% of Americans have carried credit card debt or taken on debt specifically to pay for a trip in the last two years, while 45.1% of travel card holders have let their points or miles expire unused.
That forgetfulness has a dollar figure attached to it nationally. Consumers earned more than $47 billion in credit card rewards annually, up nearly 80% from 2019, according to the CFPB. Yet cardholders also hold tens of billions in unredeemed rewards balances and forfeit roughly $500 million in earned rewards each year .
The same survey found the perks banks advertise loudest are not what cardholders actually value most. Forty-seven percent say earning points on everyday purchases is the top benefit, while welcome bonuses, heavily featured in card advertisements, rank just 7.3%, and lounge access and TSA PreCheck credits rank even lower, at 4.4%. Nearly half say their travel card is just “okay” for how they actually travel, while a similar share call it a “great fit.”
Where the fine print gets tighter and the forfeiture gets worse
Expiring points are only one layer of the catch. Federal regulators have separately flagged how issuers can quietly reshape what a balance is worth even before it expires.
A CFPB review documented complaints about sudden devaluation, where points purchased at one redemption rate suddenly buy a noticeably smaller reward months later.
Closing an account makes the forfeiture total and immediate. In the most extreme example, an issuer unilaterally closes a credit card account and the consumer forfeits previously earned rewards, since credit card companies can generally close an account without notice.
Card companies also do not make tracking easy across accounts. Someone juggling a hotel card, an airline card and a flexible bank points card runs three separate expiration clocks, a workload that mirrors how complicated flight pricing already is on the trips those points are meant to buy.
What travelers can still do before the next balance quietly lapses
None of this means travel cards are a bad deal outright. For a household that already spends heavily on flights, hotels and dining, the math in the survey still favors a well matched card over one chosen for a flashy sign-up bonus alone.
The fix suggested by the survey’s own authors is almost boring in its simplicity. Match the card’s activity to actual spending habits, and treat the rewards balance like a bill that needs checking on a schedule rather than something revisited only at booking time.
A single small purchase every few months is often enough to keep an inactivity clock from ever starting.
So the real catch is not hidden in fine print nobody could find. It was printed plainly in the survey itself, sitting in the gap between a card’s generous promise and the ordinary habit of forgetting to use it before the clock runs out.
